
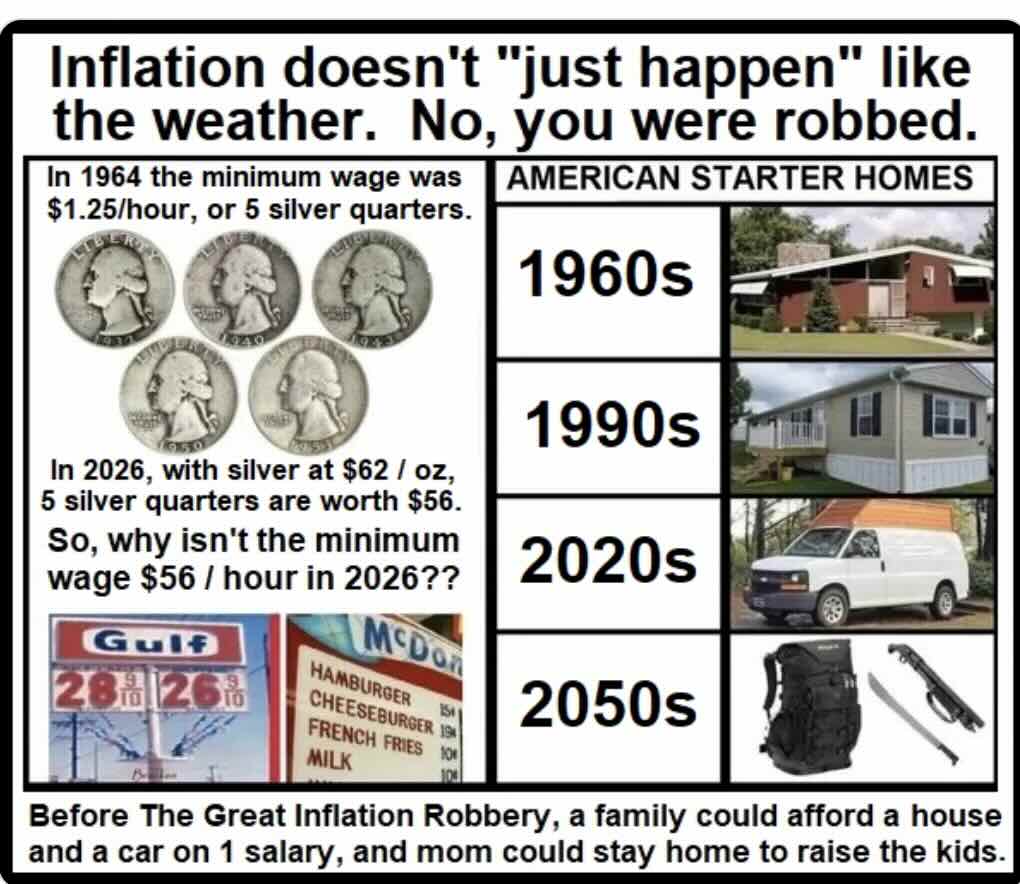

We’re told “inflation” is just needing more dollars to buy stuff – not that the stuff actually costs more. This is bullshit. I can prove that it is bullshit.
In the mid-1990s, I was working as a journalist – just as I am today only back then I was working for The Washington Times and I was drawing a regular salary. It was not a large salary. I was young and the Times gig was my first serious, full-time gig as a journalist. Yet I was able to buy a small house in the ‘burbs of Northern Virginia on my small salary. This was feasible because the monthly mortgage payment was not disproportionate to what I was being paid. I had enough money left over to indulge my car fetish, too. It was around the same time that I bought the ’76 Pontiac Trans-Am I still have today, along with a ’64 Corvair that I could afford to restore. I put a whole new interior in it, went through the engine and stripped and prepped the body for paint. I did all that making nowhere near what a doctor or successful attorney makes.
Today, I make about the same money and there is no way I could afford to buy my old house – or the old cars – I was easily able to afford back in the day. My old house – the same house – would list for about $650k today. This is about four-five times what it cost me back in the day. I would need to be earning at least four times what I earned back in the ’90s to be able to afford my old house, today. How many of you reading this are making even twice what you were making back in the ’90s? If you’re not making at least that much then you are – as they say – falling behind.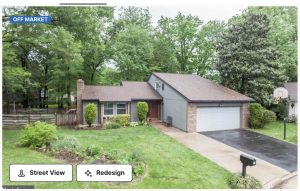
Back in the ’80s, when I was a kid in high school and college, I could afford to daily drive a V8-powered car like my Trans-Am because it only took about $20 to fill up the tank. Ten bucks was half a tank. The Camaro I drove back then (a fraternal twin of the Trans-Am I own today) carried about 22 gallons of gas. A tenner would buy half a tank or about 11 gallons. Today, it buys about 2.5 gallons. It costs about $100 to fill the TA’s tank today, which greatly limits how often I can afford to drive it. Said another way, my middle-aged self – full-time employed – cannot afford what my teenaged, part-time-job self was able to afford in the Before Time.
You have probably heard about the Great Burrito Debate, which centers on the cost of what was once dirt-cheap food. When I was in high school back in the ’80s, a McDonald’s Quarter Pounder with cheese cost about a buck thirty. I remember – I am not hallucinating this – making the run to the McDonalds just down the road from my high school when I was in high school to grab a couple plus fries for lunch. High school kids were – gasp! – allowed to do this back then, if you can imagine that. We did not have to wear ID tags and we were not locked-down in teenager prison, as today.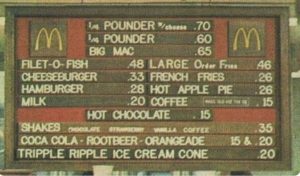
A subject for another time.
Today, a quarter-pounder is about six bucks, depending on where you buy one. In other words, one needs about four-five times as many dollars to buy the same thing today that a high school kid was able to buy back then. Eating at a fast-food joint has become almost exactly like the experience portrayed in the ’90s sci-fi/action move, Demolition Man. A evening out at Taco Bell. A fast-food meal had become a luxury experience. This has become our experience, sans the dinner clothes and live music. It easily costs $30-plus for two people to “dine” at McDonalds today. Back in the day, a high school kid with $5 in his pocket could gorge on fast food. I know because I did.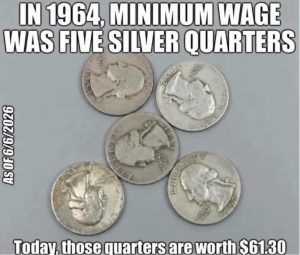
I could go on but it’s not necessary. It takes a six figure-plus income today to have the buying power that a $35k or so income could afford back in the ’90s. Yes, of course, most people are earning more today than they did back then. But are they earning three-four times as much? When even fast-food has become something most people have to be careful about spending their dollars on, it is not just “inflation” that’s forcing them to be careful about spending money on it.
“Inflation” is often presented as something vaguely natural, like aging. It isn’t. It is artificially induced, accelerated aging. It is something like going to bed one night at 35 and waking up the next morning and seeing a 55-year-old’s face in the mirror and realizing you’ll be 70 before the end of the week.
But because it happens a little bit slower than that, people accommodate themselves to it. They accept less – and paying more for it. They drive a 16-year-old car because they can’t afford a new car. They eat hamburger rather than steak. They rent a shitty apartment rather then buy a small first house.
It is a slow-motion taking-away of – ultimately – everything they had or will have. Ask a Zimbabwean about it.
. . .
If you like what you’ve found here please consider supporting EPautos.
We depend on you to keep the wheels turning!
Our donate button is here.
If you prefer not to use PayPal, our mailing address is: EPautos 721 Hummingbird Lane SE Copper Hill, VA 24079

It might be funny to start referring to the “inflation rate” as the ‘debasement rate,’ and watch the reaction of the financial classes.
Like I’ve said, there is no meaningful difference between cutting the amount of silver in the Roman coinage as the Empire slowly (and then suddenly) disintegrated, and modern inflation reducing the value contained in each dollar today. They’ve stolen something like 99.5% of the value of the dollar, but this has been done in a non-obvious way so people haven’t started slitting throats yet.
The same amount of specie (gold and silver) that would purchase a car in 1920 will still purchase a car today.
THAT speaks VOLUMES.
Labor is never given value, but is a commodity-a “necessary evil” according to the Wall Street types and is to be minimized and marginalized at all costs.
Adolf Hitler’s Germany monetized labor and gave it value. THAT is the reason that the jews went after Germany. Post WW1 Germany was successful in its economy due to throwing off the shackles (and shekels) of the internationalist banksters.
Henry Ford CREATED a market which had not existed when he paid his employees $5.00 per day when the average wage of the day was around $1.25 per day. His premise was not entirely altruistic as assembly line work was monotonous; a way had to be found to retain employees as well. Ford did remark that he wanted “the common man to enjoy the fruits of his labor”.
Of course, the wall street types and the banksters howled that Ford’s wage rates would destroy capitalism (as they knew it-those at the top reap all of the benefits while the proles are forced to live on a bare subsistence wage, due to the machinations of those at the top).
Guess what??
The OPPOSITE happened. Henry Ford knew one of the basic tenets of a truly free, capitalistic society, that a well-paid work force would be able to participate and contribute to a strong economy, unlike what is taught in business schools today-that wages must be kept to a bare minimum and that the stockholder is king.
It could be argued that Ford’s wage increases as well as the 8-hour workday, 40-hour workweek forestalled the advocacy for communism and socialism which were both gaining traction among the American citizenry.
Our “free trade” politicians have assisted the greedy wall street types and banksters in depressing wages on the promise of cheap foreign labor and products.
A good example of this is the negative criticism that Costco receives for paying its employees well above market wages. These same wall street types praise Wal-Mart for paying its employees barely subsistence wages while assisting them in filling out their public assistance (welfare) forms.
Any sane person KNOWS that in order for capitalism to work, employees need to make an adequate wage. Unfortunately, this premise does not exist in today’s business climate.
Henry Ford openly criticized those of the “tribe” for manipulating wall street and banksters to their own advantage, and was roundly (and unjustly) criticized for pointing out the TRUTH.
Catholic priest, Father Coughlin did the same thing and was punished by the Catholic church, despite his popularity and exposing the TRUTH of the American economy and the outsider internationalists that ran it . . . and STILL run it.
As an aside, today’s treasonous American government reminds me of the old Soviet Politburo with dementia-addled geriatrics running the show . . .
Another anomaly from that time – a car journalist who likes and even restores cars !!
Years ago I tried to read Keynes. It was so hard to get through the horrid tome I gave up after a few chapters. Not the Olde English snobbery, it was the fact that this is what the elites are trained to believe.
Now ordinary experience tells us, beyond doubt, that a situation where labor stipulates (within limits) for a money-wage rather than a real wage, so far from being a mere possibility, is the normal case. Whilst workers will usually resist a reduction of money-wages, it is not their practice to withdraw their labor whenever there is a rise in the price of wage-goods. It is sometimes said that it would be illogical for labor to resist a reduction of money-wages but not to resist a reduction of real wages. For reasons given below (section III), this might not be so illogical as it appears at first; and, as we shall see later, fortunately so. But, whether logical or illogical, experience shows that this is how labor in fact behaves.
Keynes, John Maynard. The General Theory of Employment, Interest and Money (p. 7). (Function). Kindle Edition.
Of course the rubes are just too stupid to see how badly you’re getting screwed over!
Keynes’s 1936 tome has been described as an ‘intricate fallacy.’ I, too, read a few pages, then gave up on it. All one can say about pursuing a PhD in Economics is that ‘a mind is terrible thing to waste.’ It far more remunerative to master the plumbing code or the electrical code: a quarter-inch per foot slope in drain lines, and E=IR. Maff, y’all!
‘Money-wage’ is an obsolete term for ‘nominal wage,’ now denominated in depreciating currency. Fed counterfeiters totally accept Keynes’s cynical fiddle of gypping workers by raising nominal wages 2% per year, while the cost of living goes up 4%.
This is how a dying empire gradually reduces living standards, while maintaining the illusion of rising [nominal] wages. It is considered preferable to workers rioting in the streets and slitting the throats of their bosses.
Death to the money changers.
Preferable to whom?
RK and Jim H,
As you observed Keynes was hard to read, but you should try to read Marx sometime….Keynes was from the technocrat school of thought…..same fallacious precepts that you can find in most computer models….the jargon and so called math are used to obsfucate and hide the fact that it’s all utter bullshit…..if you want to delve into something more rewarding, have a go at Human Action (Von Mises) or Man, Economy and State (Rothbard). Keynes and Marx essentially agreed that a society can be centrally planned and we can easily observe how that turned out in the U.S.S.R. and much closer to home…the U.S. right now. Now back to the half empty stadium of reality….
Just think the entire monetary system is based on the ideas of a homosexual Keynes.
“Man, this water sure seems to be getting warm, doesn’t it???” Said one frog to the other, in the pot of slowly boiling water…
If you think the economy is bad now, or your dollar ain’t worth shit….
Well, the (((Feral Reserve))) says, “Here, hold my Beer…y’all watch this!!!”…
And CBDC shows up, followed by “owning nothing and being happy”…for starters!!!
Oy Vey!!!
YMMV….
Taking care of our greatest ally ain’t cheap.
Who owns the not affiliated with the government federal reserve?
A printing press and instant debt fiat currency is not a reserve.
One of the underappreciated causes of the Internet bubble was the de facto elimination of reserve requirements on deposits, once imposed on individual banks at rates up to 10%. The great Bubble Maestro ‘Greenspan’ made this subversive change in 1994, with little fanfare.
Now, as you say, risk is completely centralized. Banks carry little or no reserves on their own. The Fed is the sole backstop.
This works fine until the bottom drops out, as it did in September 2008. Then Clowngress bailed out the malefactors, despite massive public opposition, and handed the $700 billion tab to hapless taxpayers. Today, it would be a $10 to $20 trillion tab.
It is quite astonishing that according to the official business cycle arbiters at the NBER, the US has suffered but two months of recession (Feb-Apr 2020) in the past 17 years. Never has this happened before. Govco says we’re partying in an endless summer of luxury and ease. But consumer sentiment fell to record lows earlier this year. What is wrong with this picture?
Gallup says 89% of Americans regard government as corrupt. This corruption extends to faked statistics. On paper, every man is a king, as Huey Long promised ninety years ago. But in reality, as ol’ Hank Thoreau fearlessly asserted a century earlier, most lead lives of quiet desperation.
Nothing is as it appears. Reality is for those who can’t face drugs.
We are absolutely getting ripped off. The Federal Reserve “TARGET” inflation rate is 2% per annum. That means they WANT the cost of living to go up 20% in ten years’ time. And 40% in 20 years’ time.
Of course inflation is MUCH higher than the rigged Soviet-tier government statistics acknowledge. M2, the money supply, roughly doubled after COVID, meaning everything has (at minimum) doubled in price in six years.
Why did they do this? To service the now $40 trillion debt (which was “only” $5 trillion in the year 2000. The government pays back bondholders in dollars that are worth half of what the dollars used to buy the bonds were worth. It’s fucking criminal. It’s the biggest scam in human history.
As someone approaching retirement age, I have a fair amount of savings that are now worth half of what they were a few years ago, which is extremely frustrating as I have been robbed of half my savings by government money printing.
For people who say “you should not save, but invest in equities,” stock prices are also inflated beyond belief. The Dow Jones was trading at 14,000 in 2008-09 when it crashed to 6,000. It is now trading at 54,000-ish. This is the biggest Ponzi in history.
In the short run, all I can do is not purchase contemporary items at inflated-dollar prices. I live in a house that is supposedly “worth” triple what I paid for it 25 years ago. I still drive cars and trucks that I bought years ago. I have a compact sedan I paid $14,000 for in 2016, and a truck I paid about $13,000 for in 2008 (including tax and shipping).
If I have to buy a new car today for $50,000, I’d be getting robbed of my life savings.
There is no way this can end well. The government cannot pay the debt. The currency cannot be debased forever. Younger generations cannot continue to pay obscene money for homes and equities. And we cannot pay for Israel and its wars forever, either.
An iron law of life is this: something that cannot go on forever — won’t.
The Fed did this:
https://fred.stlouisfed.org/series/M1SL
then everyone acts surprised where all the inflation is coming from, lol They jacked the money supply from 4 trillon to 16 overnight
Morning, X –
I despise that “invest in the shyster (stock) market” line. This was Hamilton’s line. The comedian Bill Hicks put it more earthily: Whores at the corporate gang bag. Instead of saving, spend and buy! And they push us to spend and buy – and get into debt – by punishing people who save. Der tag can’t kommt soon enough.https://www.youtube.com/watch?v=zBRpW5sEvJk
Investing is just one form of saving. Usually I suggest investing in yourself, or in your family, friends or community, but there is a place for investing in companies that do the right thing, too. If you don’t reward them for their principles, not all that many others will, either. And they go under.
Name the company, and the thing they do that is righteous. I want to check it out.
“The Federal Reserve “TARGET” inflation rate is 2% per annum. That means they WANT the cost of living to go up 20% in ten years’ time. And 40% in 20 years’ time.”
This folks is the true cost of not being able to understand math and inflation.
The total percent gain of a 2% growth rate compounded over 10 years is 21.90%.
The total percent growth of a 2% compounded annual growth rate over 40 years is 120.80%.
Math matters.
Thank you, I stand corrected.
Point is that we’re fucked either way.
Not unless you chose to be.
That compounding & math works the other way too.
Choose an investment that at least keeps pace with inflation and you at least stay while.
For people who say “you should not save, but invest in equities,” stock prices are also inflated beyond belief. The Dow Jones was trading at 14,000 in 2008-09 when it crashed to 6,000. It is now trading at 54,000-ish. This is the biggest Ponzi in history.
Let’s just say you’re right and the Dow crashes to 25000 (by 1/2) like it did in 08’.
The annualized return from 6000 to 25000 is 8.5%.
That is at least keeping up with inflation and assumes no reinvestment of dividends.
I’m not pushing the stock market – you do what you want invest in old cars that are appreciating.
Point being – don’t assume you’re fucked. Don’t be a victim of your own design.
If you are going to invest in equities, you have to understand what it is you are doing, or you stand to lose your shirt. Much of the 2008 was because of the no-doc, 120% mortgage craze of the Chimp’s Home Ownership Society, basically Clinton’s ant-redlining on steroids. As those lost value, margin calls and panic did all the rest.
The driver now is government spending. If you are confident that government will keep doing CRs and omnibuses, Cantillon says the market will “grow”. If they ever decide on austerity, I hope you cashed out the day before.
“If you are going to invest in equities, you have to understand what it is you are doing”
-Most people don’t. Hell, most “financial advisers” don’t. The simply repeat the mantra to “diversify” and that the stock “market” historically goes up 10% a year. Then they add the lawyerly disclaimer that investments are “not guaranteed and may lose value.”
I considered getting into stocks maybe 20 years ago, just before the big crash. Applying the principles of Capitalism 101, I researched stock prices of companies paying dividends that would beat 4-5% on an FDIC guaranteed CD. There were hardly any. People were bidding up share prices hoping to sell the shares to other suckers at higher prices. That’s what it was all about. Companies that were LOSING money had higher stock prices than companies that actually made a profit in some instances.
Since the market was at an all-time high of 14,000 in 2008, I declined. Following the adage of “buy low, sell high” I didn’t figure it was an idea to buy at the top of the market. I felt vindicated when it crashed to 6,000.
But I never figured they would reinflate the bubble to almost four times what it was back then. How did they do it? They did it by artificially keeping interest rates so low that people had almost no choice but to buy equities.
If you watch the stock market daily, the most important metric is usually not corporate profits or losses, but what the Fed will do with interest rates. if the Fed announced raising interest rates to 7 or 8% the “market” would collapse overnight.
The “market” is a time bomb. It is artificially incentivized by the fed and by millions of Boomers putting money into 401(k)s every single week and thus bidding up share prices, regardless of how the actual economy is doing.
In an actually “free” economy that was not completely incentivized (or disincentivized) by the government, this would not happen. Oil, gas and diesel prices are up, there is war in the Middle East, and inflation is high. In the absence of government coercion of the market, investors would normally anticipate bad economic times ahead… yet the Dow Jones keeps going up and is at 54,000.
It’s completely rigged.
Yup – so is the dollar
So are the banks (your deposit isn’t yours on demand – you become a creditor to the bank)
So are Treasuries
Pick your poison
What’s left?
Art?
Collectible cars?
Precious Metals?
Real Eatate?
Beanie Babies?
Storable Food?
So you still imagine cashing out in dollars, ultimately. The system is forever. TINA. You certainly plan to survive, however you must.
For me, how I live is very important. Unlike you guys, I can never be successful if success is based on obedience, and covid made me extremely proud of that.
What the Greenback couldn’t do, the Fed did.
For 113 years the destruction of the value of the currency has continued apace. Like with compounded interest in reverse, the exponential growth of destruction is really kicking into high gear. And it’s all to support a bloated, tyrannical, corrupt and destructive GovCo.
Breaking its teeth on the Persians thanks to the Afghanistan (aka Graveyard of Empires) debacle let’s hope that the rest of humanity will be more civilized toward us than Rome on the Potomac ever was to others.
Like Thelma and Louise rocketing off the cliff, so goes the U.S. Empire.
The Cost of Living Allowance vs. Socialist Insecurity payments. I am getting a meager SS check, having worked like a dog my entire life, and paid into it, with everything outrageously expensive, I am forced to take the monthly check or live below the poverty line and dig through dumpsters for food. I still work too.
40 years ago I was an avid Libertarian reader. I read every Ayn Rand novel, I read Murray Rothbard, and Libertarian candidate Harry Browne books, along with dozens of others. Back then there was no internet yet, alt media was reading books that did not agree with the establishment. I am old enough to remember when Ronnie Raygun appointed Ron Paul to head the Gold Commission. What came out of that was one good thing, Reagan changed the law so we could own gold legally again, including IRA’s. I also think the Treasury is selling inflation indexed bonds.
Along the way, I read how they were going to solve the Social Security payments in the future, some of those authors had figured out what the scumbag politicians were going to do, and being of sharp mind, I remembered what they wrote very clearly – they were going to cheat on the inflation update to the SS checks.
“The Coming Currency Collapse and What You Can Do About It (1980) by economist and investment analyst Jerome F. Smith is a seminal “hard money” text that warns against the structural instability of fiat currency systems. Written in the wake of the severe stagflation of the 1970s, the book serves as both a macroeconomic warning and a practical survival guide for preserving wealth during hyperinflationary crises”
They were going to fudge the accounting so if inflation was 4% they were going to say it was 2%, and make the COLA increase only 2%, thus cheating the SS recipients.
“Gold Is Money (1975) is a collection of essays compiled and edited by Austrian School economist Hans F. Sennholz. Published shortly after the final collapse of the Bretton Woods system—when the United States completely severed the dollar’s link to gold—the book acts as a rejection of fiat currency and statist monetary orthodoxy.”
One of my favorite books is The Coming Currency Collapse or another one on Gold is Money. None of those authors, and neither did I imagine how bad it was going to get. It is now way the hell worse than I ever imagined. Like the Gulf Wars, 911 false flag, Israel taking over our government, Covid bioweapon kill shit, and Trump taking the throne.
No Libertarian author every imagined a dictator as bad as Trump. We literally have the antichrist ruling the USA. I do not think it is a very good thing if we live in a nation ruled by Prince of Darkness in be with POTUS antichrist.
I asked Goolag Ai to find me a book passage I remember reading, and god damn if it didn’t find it! (in only 3 seconds!)
“search through ‘gold vs. fiat money’ books for the passage where the author sends to the US Treasury silver certificates to be redeemed in silver but instead receives federal reserve notes in return by mail.”
The famous passage you are referring to is a key illustrative anecdote found in G. Edward Griffin’s seminal book, The Creature from Jekyll Island: A Second Look at the Federal Reserve.🔎
Context of the Passage
In the book, Griffin uses this real-life scenario to expose what he terms the “illusion” of modern fiat money. He describes an experiment where a citizen decided to test the literal, legal promise printed on the front of an old U.S. Silver Certificate.
For decades, these blue-seal bills explicitly stated: “This certifies that there is on deposit in the Treasury of the United States of America one dollar in silver payable to the bearer on demand.”
The Request: The individual mailed the Silver Certificate directly to the U.S. Treasury, demanding the physical silver dollar that the note legally certified was waiting for them on deposit.
The Federal Response: Instead of shipping back a silver coin or silver bullion, the Treasury mailed back a crisp, new Federal Reserve Note (the standard green-seal fiat currency used today).
The Irony: Accompanying the modern bill was a bureaucratic form letter essentially stating that the government would no longer redeem the currency for physical precious metals, and that the enclosed Federal Reserve Note was “legal tender for all debts, public and private.
“Griffin uses this historical event—which timeline-wise represents the window closing on silver redemptions in June 1968—to argue that the government effectively defaulted on its contract with the public. He highlights the absurdity of the exchange: a citizen sent the government a paper promise for real money, and the government “redeemed” it by sending back a different piece of paper that promised absolutely nothing.
In Chapter 7 of The Creature from Jekyll Island, G. Edward Griffin details an exchange where Ohio resident A.F. Davis mailed a ten-dollar Federal Reserve Note to the U.S. Treasury demanding “lawful money”. The Treasury responded by sending two five-dollar bills and a vague definition, ultimately failing to reply to Davis’s final letter pointing out the circular logic that paper was merely being redeemed for more paper.
Today, the Treasury would keep Davis’s ten bucks, and then send a criminal referral to the US attorney for mailing cash, which is prohibited.
Freedumb! 🙂
>mailing cash, which is prohibited.
Not true.
https://www.federalregister.gov/documents/2023/03/08/2023-04475/mailing-currency
Eric’s essay is thoroughly explored in this book:
The End of Freedom: How Our Monetary System Enslaves Us (The preppers’s guide to surviving economic collapse and loss Book 1)
by John Thore Stub Sneisen (Author), G. Edward Griffin (Foreword)
The end of Freedom: How our monetary system enslaves us.
In the End of Freedom, the author John Thore Stub Sneisen shows us how throughout history the current type of monetary system has helped to keep the people in control of it wealthy and the people using it poor. By the creation of money directly by printing it or by lowering interest rates on debt and therefore making money easy to access, but the people accessing the cheap money are losing as the money they make loses value and buys less over time. Also it makes it harder for them to pay back the debt they have accumulated. Bankers and other people with money will be able to loot the countries going bankrupt and having to sell off their commodities and land to pay off the debt.
What Has Government Done to Our Money? by Murray N. Rothbard
Another book which covers Eric’s essay in full, read it for free right now:
https://dn760100.eu.archive.org/0/items/what-has-government-done-to-our-money_202204/What-Has-Government-Done-to-Our-Money.pdf
YJ,
>They were going to fudge the accounting so if inflation was 4% they were going to say it was 2%, and make the COLA increase only 2%, thus cheating the SS recipients.
They are doing that right now, except the spread is much more than 2%.
See my post below.
Plus the IRS taxes my SS benefits even though I already paid the taxes on the money going in, double taxation for sure. “No tax on Social Security benefits” – another of the multitude of Trumpenstein’s lies.
I just spent $30 on a quarter tank of trump joo war gas…figured it’d go up again bc the orange idiot launched another series of attacks on Iran. Fucking traitor.
My story mirrors Eric’s. Bought my first house in the 90s. It was less than what a new half ton truck is today. On paper I make significantly more. In reality I’m doing worse because of my government.
***RON PAUL WAS RIGHT***
https://www.youtube.com/watch?v=MCYZ14Ti4vc
He was right then, he’s right today.
Wall-humping Ron Paul’s wall-humping son Rand voted in favor of merging the US military with the IDF. Ron has always had a wimpy persona, frail body and a high voice, and he raised a son who was beat up by a shrieking leftist and voted for that. Ron Paul was allowed to exist because he makes people associate sound money and libertarian principles with an ineffective wimp with no chance of winning anything. If only a Jessie Ventura or Arnold Schwarzenegger had the same message.
Though imperfect, Ron Paul is a 91 year old, learned, decent man of principle. Imperfect as well, maybe even more so, Rand Paul is his own man. There is a certain incongruence with cartoonish and fake tough guy personalities like Arnold and James Janos who always “win” in the movies and in real life when promoted by “winners” like Jeff Zucker and live and let live libertarianism, let alone doctrinal libertarianism. Such poltroonery is much better suited to shilling for masks and vaxxes while uttering things like “screw your freedoms.”
Well-said, Funk –
No one is perfect and those who decry flaws in others usually have worse flaws. Ron Paul is a decent man. Jimmy Carter was a decent man. I think more decent men would be a good thing. As an aside, I do not think that a decent man must be “wimpy.” In fact, the ancient definition of gentleman encompassed the idea that he was man very capable of not being gentle – when the situation demanded it – but held it in check until the situation demanded it.
In 1991 Wife and I were able to build a decent house, install a well and septic and 1/8 mile of road for 60 grand (Land was already paid for)…Try that now. House now needs 2 times its cost in repairs and upgrades… Between the covid hoax and the EV bullshit I lost my good job in automotive plastics……Everything sucks now.
Hi Eric, et al,
One can put this in the context of what a dollar would buy say in 1950 vs. today and that’s instructive. What makes more sense to me is to look at the slope of the curve on “inflation” (which technically is expansion of the money supply).
Here are two interesting factoids….
1) the debt was IIRC ~$19 trillion when Trump was elected in 2016…..it now has gone over $40 trillion.
2) the dollar has lost ~33% of its purchasing power in ten years, which includes Trump 1, Biden and Trump 2.
Let that sink in for a moment. The effects of what people call Modern Monetary Theory include currency debasement at an ever increasing rate….it’s bad now and Trump and company are manipulating things such that they steal billions while ordinary citizens suffer. These are signs of imminent turmoil.
The answer is secession…..it’s coming sooner or later. I feel no compelling reason to help pay for the mess these mongrels have made…let them figure it out….of course that’s not how it works…but they say I am a dreamer, I’m not the only one…(apologies to JL)
Just remember: The Experts say, ‘Ideally, inflation should be kept at 2% in a robust economy. This is why Henery Ford went broke selling the Model T and the Electronic Industry is in such dire straits.
This Keynesian position has some psychological truth. Their logic is aggregate demand drives the economy and thus the flow of money. This of course is an academic reduction but it works in the real world in the sense that people are reluctant to buy something if they think the price will go down, which freezes up spending and the velocity of money slows.
There’s exceptions, computers in the 70s to 90s bucked this because demand to buy and upgrade was mostly real. You got true innovation and legitimate reasons to replace. Many consumer goods followed this. Cars too for much of the middle 20th century. You bought one because it worth buying on aesthetics or merit so the price was what it was, you were likely going to pay whatever it cost as long as it was reasonable.
When a widget becomes fungible a person is only buying on price and the real pressure is always to go down as R&D is recouped and manufacturing scales with greater efficiency. With almost everything now there is no real driving reason to buy anything so most people will wait until it breaks or the price goes down.
Inflation as an artificial monetary mechanism across the whole economy addresses this by making everything constantly cost more. It removes the mental block most dullard “consumers” have in their mind to wait for price to go down. They don’t realize they’re being manipulated in this way but they are. The FED owners know exactly what they’re doing and it works as long as the inflation is small and unnoticed. The thorn is it’s never perfect and sometimes they lose control, an economy-wide panic.
Still, the basis of the arguments being made are true, things do cost more. If nothing had changed the average salary would have also inflated and relative buying power would stay fairly consistent.
What is left unaddressed in this analysis are two things.
One is the housing market became speculative, people flipping to build fake equity. It’s the opposite effect as prices going down over time. House prices grew faster than inflation due to constant moving up in McMansion and AirBNB and ADUs. The fear of missing out drives a minor frenzy that’s been sustained in housing for about 30 years, driving prices up faster than they should. There’s also actual demand, the number of people in this country has gone from 200 to 350 million compared to 1996 but the number of houses has not increased by the same proportion, so there’s true demand and supply at work to some extent.
Second to perceived wealth is the amount of stuff people get, very little of it actually useful. Back in the 1990s we had basic electricity, water, phone bills, maybe a car payment, and rent. We made due with an older car, no A/C, a few drawers of clothes, bought durable things. Most people were simply more frugal.
Now people convince themselves they need new fashions, a cell phone, broadband, a dozen subscriptions, a constant stream of gadgets from Amazon. Cars don’t last, products are made “smart” and break. So people are less wealthy because the average person wants to appear wealthy by the time they graduate high school. I didn’t even have a credit card until I was half way through college and that was only used for books. On this point what I’m saying is people buy so much more junk they don’t need, which puts pressure on their salary, too.
Hi Eddie!
This is well-said. I will add that – in the past – (as recently as just six or so years ago, before “COVID”) it was possible for a person to avoid much of the pernicious effects you describe by living modestly. I have always done this. Yet I find it no longer is as effective (to put it mildly) as it was. For example, I drive old, low-value vehicles to keep down my costs. Yet even though my truck is 25 years old and even though I haven’t even gotten a seatbelt ticket on my driving record (and zero claims made against me or by me) the cost of the insurance I am forced to pay has more than doubled in just the past three years. I can do essentially nothing about this – other than just stop paying and become “uninsured.”
When my ’02 Nissan was new, it listed for about $14k. That meant I was able to buy it when it was about five years old for $7k. Cash money. Today, you cannot buy a new truck – I mean a real truck, the Maverick isn’t one – for less than about $32k. After five years, that truck will sell for $22k and who can stroke a check for that?
Medical care will bankrupt you – so they bankrupt us via “health insurance.”
An “evening out at Taco Bell” is now an extravagance.
Obamacare removed the ability for young people to reap the benefits of youth. They get to pay into the health care scam from their first paychecks rather than avoid it for a long time, like us. Health insurance? OK, sure, when I’m old I’ll think about it. They’re also not healthy, which is a compounding effect.
I’ve pretty much always had car insurance but maybe it’s just me. I’ve worked around the exploding costs by using an umbrella policy.
I’m not sure you citing your 2002 pickup is fair since the average person can’t drive someone else’s car daily, keeping miles and wear at bay. I have a 2010 truck that’s getting tired with 260,000 miles on it because it’s got to be used 365 days every year. How often do you really drive your own personal cars? And I bet when you do it’s the fun car anyway.
Hi Eddie,
I have always driven my personal vehicles regularly. The TA is for occasional roughly five mile jaunts around the backroads near my place. I do not drive it more than about 500 miles a year.
ObamaCrap was indeed a major “screw the young”. Not that most of them recognize it…
Re: high mileage vehicles, not a problem with anything built since about the time of OBDII up until maybe 2015. Not from that, per se, but roughly that is when the reliability went way up. My wife’s car has 180k on it now (and is getting ready for its third friggin’ clutch), but the next lowest car in our garage has 290. One has over 500. It’s all in the maintenance. Abuse your equipment and it will break.
Insurance is heavily dependent on region. Whether its PC to say or not, living in proximity to illegals (who usually have no insurance at all) necessarily means your rates skyrocket.
We are talking apples and oranges. Personal income is nowhere near Household income.
>Personal income is nowhere near Household income.
How is that?
Do you believe in Santa Claus?
Or maybe only the Easter Bunny?
Personal income is, well, personal. How much you make. Household income is how much your entire household makes.
Hi Ken,
I was single (one income) when I bought my first house.
I was thinking more like what Steve was referring to. Family income is what the US gov is referring to. The Gov through inflation has stolen most single income so to keep the number$ in the same ballpark they went to Household Income. A feint if you will. As you can see,,, worked like a charm. We need to remove the blinders. Clowngress needs to vote for anything Off Budget or Over Budget. And it needs to highlight the amount over Budget.
Roger that, Ken!
>The fear of missing out drives a minor frenzy
https://en.wikipedia.org/wiki/Extraordinary_Popular_Delusions_and_the_Madness_of_Crowds
“Last in” are the suckers. One born every minute, as Mr. Barnum observed.
About 2% inflation. It is still theft, and in 10 years that is 20%. And savings rate at your credit union or bank is still near zero. You should be getting the inflation rate plus a premium on top of your savings.
When the Fed started targeting 2%, they have admitted they can not stop inflation…. furthermore, since when is inflation a flat 2%? Never.
Why do governments exist and what is their purpose? Compare that to how they actually operate and who runs them. It is clear the US government is run by criminals, who are looting the nation while they attack and steal shit from others.
The people of the United States are a captive population by a gang of criminals. They are bleeding us while the loot. They use the media and language to keep us from revolting. They massage the data to make inflation look less than it really is, they intentionally obfuscate reality and present a false narrative. Always lies, always theft, always murder.
Then we go to the voting booth and re-elect them. So who is to blame, the criminal class of politicians or the people who not only tolerate them (by not revolting) but vote from them to get some of the loot? Look at how many people get grants or write papers supporting the state narrative on climate change. If you want the money you must support the narrative – so there is a whole class of liars who use their science skills to fake the global warming data the state needs for the rest of the agenda, like the control they have over the car industry.
As time goes on, and the decades pass, the control over us goes up, and everything turns to shit. All cars look the same, all cars become monitoring devices, and soon we won’t own or control our personal transportation. Entire army of government workers keeps the system in place, if you try to get a car they won’t approve, you become a threat to the state.
Trump comes along and promises us he will undo the damage to our free society, he is going to make us great again, promises a bright future. Soon as he gets in he does the exact opposite. People complain, but no one has the courage to kill him. Trump knows that, he knew exactly what he was doing all along, lying like a snake to get elected, then serving the satanic deep state objectives.
Take a look at Ukraine, where decades of severe corruption is now playing out the end game. The situation in Ukraine is so bad half of the people fled never to return. They are grabbing kids off the street in forced conscription drives, they are fighting a losing war against Russia and Zelensky (totally corrupt Jewish homosexual war making maniac) refuses to sue for peace.
Like in Amerika, no one has the courage to kill the leader who is screwing the nation over killing off the people. Why has no one killed Trump or Zelensky? They have addresses, they have to give public speeches. Thousands of Ukrainians are building attack drones, why are they not using drones on der leader who is destroying their nation. Same for Trump. Why isn’t Trump being attacked by waves of drones from angry citizens?
Because we are a nation of sheep being ruled by wolves. Those that are willing to kill are in charge, and those who are cowardly are the slaves who willingly allow themselves to be taxed for their own enslavement. The wolf class is highly organized while we are unable to even form a third political party.
I wonder, do the Amerikan tax slaves have the courage to vote for Thomas Massie and MTG?
I am not convinced most people even have the balls to vote outside of the box they are in. How bad does it have to get before the people revolt? Look to Ukraine for the answer. The nation will rip itself to shreds before there is any reform.
If the Amerikan people want to save themselves at this point it is obvious they must reject both main parties and vote for nationalists and no Jews. But do Amerikans have the balls to vote against Jewish control? I doubt it because they are brainwashed by the Jew unholy book.
Assassinating Trump would have exactly the opposite effect. They become martyrs. Whichever faction did the deed would be branded terrorists, and treated accordingly.
You don’t even have to go to the level of assassination to see it. If they want to take down a troublemaker, at the pre-raid briefing, you just tell the sharp points of the spear that he is a child molester or something similarly bad, and the raid will go down with lots of itchy trigger fingers.
Hi Steve,
Yes, I agree. What ought to happen – but won’t – is that the Republican leadership (ha!) visits him privately and tells him he can either step down for “health” reasons or he can be removed, via proceedings. This is what happened to Nixon – who deserved it far less than this loathsome old oaf does.
I don’t know that he’s the problem. It’s definitely not him if you are right about the joooos.
But I do know the Republican’t leaders are a big share of the problem. They can somehow end up on the 20 end of every 80/20 issue.
Hi Steve,
His outre, indefensible conduct – including his asinine memes – is most definitely a problem. It’s gratuitous, unserious and contemptible. He’s an embarrassment.
He’s crude and boorish, yes. How well did we do with Mr. “First mainstream African-American who is articulate and bright and clean and a nice-looking guy”?
Frankly, I’m sick and tired of the smooth operators who have handed over the country for the last century or two. It’s time to try something, anything different. Or get rid of the whole frikkin’ institution and let the chips fall where they may.
The perfect ruler must be out there, somewhere. The only danger is not having one.
@Steve “Assassinating Trump would have exactly the opposite effect”
I strongly disagree and hear that lame statement all the time, not just here, but also on the Unz review.
First of all if the politicians are getting killed, they will the KNOW they are not invincible and will instantly start taking their job more seriously and stop caving to special interest, AIPAC, or Israel.
Second of all, Trump is a rare charismatic leader as is Zelensky, Putin, Hitler, Churchill. Killing the charismatic leader is very important. There is no one to replace them with. Trump is using his charisma to do unspeakable things. Killing Trump is essential to restoring sanity.
Third, the funeral of the dead prick like Trump will expose the scumbags that still support him, including foreign scum.
4th. The scumbag liars in the alt world and MSM alike will be expose when they condemn the assassin. Like Nick Fuentes or some other gay perv who comes to the defense of the dead Orange Caligula.
No decent person should want Trump alive right now. No decent person would condemn his assassin.
No decent person would attend his funeral.
Wake the frack up, Trump should be killed and it would be a damn good thing. Stopping Trump with a bullet now will save thousands if not millions of lives, it may even stop WW3.
Trump is a mass murderer. Trump is a serial pedo rapist. Trump is a thief and con artist. He deserves no respect and has forfeited his life by his own actions. How many people does Trump have to kill Steve before you too agree Trump should be assassinated?
“they will the KNOW they are not invincible and will instantly start taking their job more seriously and stop caving to special interest”
Not a chance. They will instead vote for greater security. Guards with much fewer rules of engagement. Shoot on suspicion.
Is this the first exposure you’ve ever had to congresscritters and how they respond to incentives?
Hi Jack,
I have a bottle of champagne in the fridge, looking forward to popping the cork when Treasonous Trump dies, however it happens; hope it’s drawn out and painful.
“Yes, of course, most people are earning more today than they did back then. But are they earning three-four times as much?”
According to the data, pretty much.
https://fred.stlouisfed.org/series/MEHOINUSA646N
I’m not saying inflation is good. It’s the exact opposite. If not for CONgress’ profligate spending, deflation would be the norm. Forget about pre-66, four of those post-66 quarters would buy a burger, fries and shake, and you would get change back. Of course, you would still have a median income of $22k, but in a world of generally falling prices, that would be increased buying power.
The salary we’re paying new college graduates where I work (utility company in large western city) at $90k, which is slightly more than 3 times what I was paid when I started in 1994 ($28k at Worldcom). Some fields for engineers you start north of $100k and I’d expect a similar starting position to mine to pay more like $120k now.
I don’t suggest this is a broad market indicator since I’m an engineer. The demand for people is always lagging supply. It has since I started with almost no exception. Things got a little competitive after the dotcom bust but I moved from network (was rolling out and provisioning fiber) into more traditional electrical (power distribution).
That move was wise in 2008 when there was basically no risk of me getting laid off since people will always demand the lights come on. We are really thin on staffing but that’s not for lack of trying, there’s a dozen unfilled positions just in my office. It’s not sexy AI datacenters or ‘full stack’ front end developers but that to me seems like dotcom all over. Give me boring and steady any day.
Some fields are paying way less. For example Eric’s field is in the shitter comparatively and that’s not really any fault of his personally. The media shot themselves in the foot by becoming paid political liars for the oligarchs and in the process destroyed the reputation and marketability for newspapers and magazines and diluted the TV and radio world with 100 channels of shit on cable.
-anon
Another pisser is the office drone overhead non productives get the money, direct employees “boots on the ground” get peanuts. Family member is a university instructor (non tenure, that’s a fading relic now). $65k is pretty normal for full time. Meanwhile the administration realm expands continuously. They create ‘play office’ positions “Director of Native American Relations” you name it, they have a spot for this BS. ALL these useless admin jobs pay well north of 100k to start. State government the same drill.
Spot on. Look at any school district, the number of administrators has exploded while teacher-to-pupil ratios has stayed about the same or even gone up slightly. Ignoring the underlying fallacy of taxing and public school for the moment, teachers do get the shaft but that’s because the total number of employees has doubled while the pool of money has not. All those masters of education planners in the district HQ add nothing of real value but they suck up pay. But then it’s their own union’s doing. As a teacher ages and gains experience they can’t be “just” a teacher their whole career. No, they have to become a paraprofessional so more and more position are created to give the appearance of a lifelong career path when there should not be any such thing. Teachers used to be either young, a job until they got married and dropped out of the work force, or something they’d do to supplement a husband’s salary after the kids left the house.
>Teachers used to be either young, a job until they got married and dropped out of the work force, or something they’d do to supplement a husband’s salary
Either that, or Old Maids, women who never married, in which case it *was* a lifelong career.
St. Clair Shores Michigan is approximately 12 square miles in area. They have 3 school districts within this small area.
That means 3 superintendents, multiple school board members, facilities managers and teachers out of proportion to that community’s size.
Talk about waste…
My first full time job after university graduation, starting Sept. 1970, paid just over $8000. I worked for a consulting firm, and my job title was “Junior Scientist.”
I was engaged in air pollution measurement and control, and electric power utilities were among our customers (EPA compliance). My colleagues all had engineering or science degrees, of which some had advanced degrees.
Using BLS CPI calculator:
https://www.bls.gov/data/inflation_calculator.htm
$8,000 (1970) => $68,000 (2026)
If your new hires are getting paid $90,000, they are doing considerably better than I did, at least on paper. 90/68 = 1.32
But now let’s look at housing costs.
I paid $67,000 for the house I bought in 1981, where I still live.
Again applying the CPI:
$67,000 (1981) => $240,000 (2026).
Fact is, the market value of my house is $600,000 $19,300 (2026).
One local Ford dealer is advertising a 2026 F150 for $40,900.
40.9/19.3 = 2.12
My conclusion?
FedGov is *LYING* to us about the actual cost of living increase.
The bogus BLS CPI calculator *grossly* underestimates the *deliberate* currency devaluation. Wilkommen nach Weimar.
My prediction?
The fraudulent BLS CPI is the way FedGov plans to “fix” Social Security.
Perhaps I will get lucky, and die before I have to either a) eat dog food or b) rob a bank, to live. As a 77 y.o. male, the demographics favor that outcome. Failing that, there is always self-termination. Should I eventually elect that option, as a “useless eater” (Lebens unwertesleben) I will *not* require “medical assistance” (i.e. lethal injection), only a plastic bag and some duct tape, a.k.a. the Robin Williams (R.I.P.) method.
Interesting that “medicallly assisted suicide” uses *exactly* the same technology as the execution of condemned felons. What does that tell you about our society?
“Rage, rage, against the dying of the light.”
— Dylan Thomas
Well-said, Adi –
There is a subtext to the position that the cost of living hasn’t really gone up that really annoys me. It is the position espoused by greasy little shitstains such as Ben Shapiro, who says things like “move to a more affordable area” or (per the GOP) just work harder, you lazy SOB!
The fact is most people have to take out a loan to buy a shitty, ten-year-old used car. People used to commonly pay cash for decent used cars.
The fact is that anyone who wants to buy an average new home – about $400k – must come up with $40,000 in cash for the 10 percent down payment.
The fact is that $100 buys a couple of bags of basic staples at the supermarket.
We are being enserfed and enshitified and we’re not supposed to notice or complain!
>“move to a more affordable area”
Hey, Eric,
Fact is, when I bought my house in 1981, it *was* a “fixer upper”, (a.k.a. “deferred maintenance”), and the “bargain rate” loan cost me 16.25%. You read that right, kids.
Fact is, as a journeyman carpenter and master builder, I have worked very hard to improve the property, over the course of the 45 years I have lived here. It is a nice, stable, mostly peaceful neighborhood in an older (though not officially “historic”, thank God) part of the city. Comfortable, though not “fancy”, which suits me just fine.
I *have* lived in a neighborhood so dangerous you took your life in your hands to step outside your front door. (Hyde Park, Chicago, 1970-71, where the n*ggers will slit your throat in broad daylight to see if you are carrying anything worth stealing.)
Let Ben Shapiro go live in the ghetto. I ain’t going back. 🙂
Hi Adi,
Yup. My old house – my first house – was similar. Rotting T-111 siding; slab with foundation cracks. Termites, too. But it was mine, dammit – and I was very proud of it. I re-sided the whole place; replaced the windows (single pane shit from the early ’70s) and put down nice laminate flooring and pretty much fixed everything else that was wrong with it.
Copy that. 🙂
Hi Eric & Adi,
We bought our house in 1974 for $33k, interest was 7.5% at that time. It was also a fixer-upper, which was how we could afford it. It’s an old Victorian (1863) with 12 foot ceilings and 7 foot tall windows; solid construction but needed lots of updates, especially insulation since that was right after the first oil price shock and heating costs were through the (uninsulated 😆) roof. Did all the work myself with occasional help from friends when the job required extra muscle, most all of us back then did similar, it still amazes me that most people today can’t do squat besides look at their phones. I wonder if was part of the establishment’s plan to infantalize the population by taking shop class out of the schools.
In any case we’re still here after 52 years and am not about to let them run me out, molon labe motherf*ckers.
P.S. according to Zillow our house is worth about $1.2 million…..with the property taxes to match.
Hi, Mike,
> especially insulation
LOL.
Mine was built in 1956. Zero insulation. I got all scratchy pushing R30 fiberglass into the attic. Builder (likely owner-builder) had absolutely no clue about drainage, so I had to fix what I could, to prevent flooding.
>Did all the work myself
Mens et manus, eh? So much fun…
Book in one hand, hammer in the other. 🙂
>Victorian (1863)
IIRC, you said your house originally had gas lamps, as did the place where I lived in Cambridge during 1970-1971.
It did have gas lamps Adi, I left the pipes in the wall when we renovated, used a couple as conduits to pull wiring through.
Correction:
Market value of my house is $600,000 < [value] $19,300 (2026)
One local Ford dealer is advertising a 2026 F150 for $40,900.
40.9/19.3 = 2.12
FWIW, same house in Pasadena (LA County) or Costa Mesa (Orange County) would be worth about double. Location, location, location.
Fortunately, due to Prop. 13, my annual property taxes are still <$2000. Thank you, Howard Jarvis.
https://en.wikipedia.org/wiki/Howard_Jarvis
Housing was at record levels of “affordability” just a few years ago.
Used to be easy. FRED ran a series of mortgage payment relative to household income. That has been discontinued.
Look up median house price (unfortunately, the series also appears to no longer exist, having been replaced by median new house price, which includes mcmansions and eliminates the traditional starter home category, but gives a good upper end on affordability), median income, and interest rate, and plug those numbers into any loan calculator.
Use any source of data you like. Here’s the ones I used.
https://fred.stlouisfed.org/series/MSPUS
https://fred.stlouisfed.org/series/MEHOINUSA646N
https://www.bankrate.com/mortgages/historical-mortgage-rates/
Incidentally, look at that first link. Housing prices increased by a whopping 1/3 from 4Q 2020 to 4Q 2022. And the interest rate graph shows a 120% increase in interest rates at the same time, with a typical lag. There’s your unaffordability right there.
“ Should I eventually elect that option, as a “useless eater” ”
There is another option, though I’m not sure what a gentle euphemism may be, perhaps a safari hunt of sorts for various predators.
https://en.wikipedia.org/wiki/The_Most_Dangerous_Game
As I was saying …
Record-High 89% in U.S. Say Government Corruption Widespread
Substantial majorities of Republicans, Democrats and independents agree
‘Americans’ perceptions of government corruption in the U.S. are at their highest level in 20 years, with 89% of U.S. adults saying it is widespread. That figure is up 10 percentage points from last year and well above readings in the 72% to 79% range between 2010 and 2025.’
https://news.gallup.com/poll/713933/record-high-say-government-corruption-widespread.aspx
A government which finances itself by counterfeiting is axiomatically corrupt. And its corruption trends in only direction: UP.
Dishonest currency fuels dishonesty throughout every nook and cranny of a culture. The Federal Reserve is a temple of fraud and chicanery, which (naturally) refuses to be audited. Burn it down. Then loot it bare.
The counterfeiting (inflation) is readily apparent in the price of gold. Buying gold is not significantly profitable, in terms of real value, but one of few means of keeping your value. Counterfeiting is one of the few criminal acts described in the Constitution. But then again, theft is one thing the psychopaths in charge do almost as well as they kill people. Almost.
A couple of things: I got out of college in ’89. I remember the Credit Union ATM at work dispensed $5 bills. I was (kind of) a broke new employee/recent college grad so I worked by spending that way, $5 withdrawals at a time. At any rate, I distinctly remember, that that $5 would buy me a McD’s Value Meal and a pack of cigarettes for lunch!
I think our generation was pretty much the last to be able to put ourselves thru college. Hans Gruber’s comment about no wonder the young generations are turning to socialism/communism is spot on.
And we wonder why young people are flocking towards socialism/communism.
I went to state college (where I learned the least of what I know today with a couple of exceptions) for about $2000/year in 1982. That is $7,000 in today’s dollars if you believe the CPI. I was able to pay my own way without a loan but just from my wages as I was also working.
Besides public grade schools and colleges are now indoctrination centers for Marxism, they enslave young people for the rest of their lives with student loan debt you can’t even bankrupt away from yourself. Just like what the Nazi’s-Socialism-Hilter, Communist-Lenin, Stalin did, you have Marxist promising something for nothing. *Hmmm…can’t get a good paying job…it must be Elon Musk’s fault. Let’s strip these guys of their riches…yea! The reason you are poor is because they are rich!*
Also, tempting them with dissolving their student debt. It would sound enticing to me too if I were in their shoes.
We are at a dangerous tipping point.
Ditto that, Hans –
I was a few years behind you, but was able to pay my tuition at George Mason University in the late ’80s working a night shift at UPS unloading trucks. A few years later, I was at the Times and – trust me – the Rev. Moon did not pay well – yet I was able to buy my first house and never thought twice about what food or gas cost.
People who do not grasp the situation – especially as it affects people in their 20s and 30s today – are fools and thanks to such fools, we’re probably all going to pay for it.
Agreed. The feds throwing all that money at colleges was death. People who had no aptitude for college were going, because you could get all that money for “free”. Colleges responded by creating majors that the lower end of this influx could sort of handle. Everyone except the 5% or so who belonged in college understood that there was no way most people were going to be able to pay it off by asking, “Would you like fries with that?”
In the future post mortem audit, I think that will turn out to be the single worst action ever taken by the feds. Worse than NFA, the 16th Amendment, the Federal Reserve Act, the Selective Service Act, the Federal Procedures Act, heck maybe worse than all of them combined. For exactly the reason you gave. It put lower intellect people into permanent debt servitude.
Old Tricky Dick removed the final backing of the Dollar by gold in 1973 to keep foreign nations from making a run on gold reserves. it’s been a slow motion wreck and speeding up since. Just wait until the world drops the dollar as the reserve currency and will get to witness Weimar Republic 2.0.
As most know, the Federal Reserve counterfeiting operation was established on Dec 23, 1913, in a ‘law’ signed by Woody Peckerwood Wilson.
Less well known — I found this in a series of charts detailing the components of the Fed’s balance sheet over a century — is that gold constituted the Fed’s largest holding until midway through WW II, when Treasury bills surpassed it. This was a classic example of inflationary war finance. Gold continued dwindling to become a minor footnote today, within the Fed’s massive holdings of Treasury and mortgage debt.
Sadly, the gold clause in the Constitution is incompetently drafted: ‘No State shall … coin Money; emit Bills of Credit; make any Thing but gold and silver Coin a Tender in Payment of Debts.’ What the hell were they thinking — this language places no bar on the US fedgov, which afflicts us with all of these depredations.
Never mind the details: we live in regime which finances itself by counterfeiting; publishes fake inflation statistics; proclaims that 2 percent inflation (based on fake statistics) is ‘price stability’; always errs on the high side of its 2 percent target anyway.
In the 19th century, counterfeiting was widely regarded as a capital crime. In the 21st century, we are governed by patently dishonest counterfeiters. All other evils flow from institutionalizing government criminality. No DemonRat or Repugniclown will even speak of this. Like petty pimpmasters, they support themselves on the proceeds of crime and vice.
Needless to say, a criminal empire has no future. The only question is when everyone turns to crime, violence and chicanery, aping the model presented by our bent ‘leaders.’
Now I love them cowboys, I love their gold
Love my uncle, God rest his soul
Taught me good, Lord, taught me all I know
Taught me so well, that I grabbed his gold
And I left his dead ass there by the side of the road
— Grateful Dead, Me and My Uncle (1970)
Food for thought, he “beloved” federal income tax amendment was passed with the explicit idea that it was to be applied to those robber barons, with the income to be taxed starting at $3000… when $3000 was denominated in gold at $20/oz. So the federal income tax was to be applied to incomes above 150 oz Au/year, or at the current $4368/ Troy oz, incomes above 218400/year.
Democracy, giving the rubes what they want, good and hard, without lube.
That song was the first set acid afterburner.
My wages just over doubled whilst my house has gone up around 5 times as much. The renovations carried out are partly responsible but mostly due to my buying a run down fixer upper with more expensive houses all around me. So at least once in my life I bought smart.
I joke that I live in a house that I couldn’t afford to buy today.
I don’t have a solution to this problem though either.
Same here, Landru –
I could never afford to buy my current house today. This, by the way, is why I feel great sympathy for Gen Z. They see Genx’ers (me) and Boomers who “got ours” and resent that they aren’t going to get theirs. Of course, it’s not GenZ’s or the Boomers’ fault. It’s the god-damned Fed and the government’s fault.
But we’ll probably get confiscatory communism anyhow.
Took a long time for my wages to double, but they doubled, then doubled, then doubled again over 25 years in the same profession. All while everything else did the same.
I couldn’t afford my current hose today. I only purchased it 2021, and still, it has gone from 220K to 380K. But that is a result of location, and demand. People moving to Az in droves, although too many ar communists who should have stayed put. I long ago had a very financially savvy uncle who taught me about real estate. He told me always buy the smallest, shityiest house in the best neighborhood you can afford. Plan on holding it at least past the capitol gains exemption, or 3-5 years and you will most likely come out ahead. I’ve done this five times, and always made money. Although the money I made didn’t always keep up with the inflation. To do that you have to be a real wizard. You must pick the next rising asset class right 9/10 times. Still I got it right a few times with PMs, vacant land, assets that go boom, and certain stocks. But, inflation, like rot is still insidious and ever present.
I do not enjoy-joy. the federal reserve/government printing my purchasing power away into the ether. I realize not everyone should own a home. Some people are only suited to be renters. If you cant afford it without fancy ARMs or government assistance, or, you are buying at or near the top, then you should probably rent. I did until I was in my late 20s.
Wish there was something I could do for people my kids and grandkids age. It’s much harder now and they are right to resent those of us over 40. We should have been hoisting black flags and slitting throats 30 years ago. If we come together and identify, then remove our common enemy, the situation might get reversed
“ Yes, of course, most people are earning more today than they did back then. But are they earning three-four times as much?”
The nominal median U.S. household income was $29,943 in 1990 and is approximately $85,000 in 2026.
Hi “Burt,”
Yeah? God luck buying a $400k house – average price now – on $85k income.
The name change shit is just so damned tedious.
Mean house price doesn’t say much for the same reason averaging in Musk into mean income does — because there are so many multi-million dollar homes bringing the average up.
As of 4Q 2025, well over half the homes would qualify on an $85k household income. It just means you can’t necessarily live within easy commuting distance of major blue hellholes. Though that has been true in Southern California since at least the ’80s.
https://www.nar.realtor/research-and-statistics/housing-statistics/county-median-home-prices-and-monthly-mortgage-payment
Well, Steve –
I live in a rural one stoplight county in SW Va. A place where you could buy a couple of acres and a single wide for $75k when I moved here after I fled Northern Va. My house is now beyond my means; the only reason I can live in it is because I could afford it when I bought it. Across the road from me is a nothing-special old house on four acres. It is up for sale. Asking price? $500,000. It would have sold for maybe $175,000 before “COVID.”
Right. VA is being taken down as we speak. Or maybe it’s already dead. Sounds like the latter, from your anecdote.
Around here, nothing special land is going for around $10k an acre. Unless you are willing to spend a million on a bigger chunk. Then its somewhere south of $5k. I have no idea what a single-wide costs. Add probably $8k for septic, $1k for well, maybe $2k for utilities hookups.
When my Irish mother in law mentions her great-great grandfather who came from Ireland in 1850-something and went to work on the railroad for $1 a day, which worked out to $20-25 a month, and he was paid with a $20 gold piece at the end of the month and a silver dollar for each extra day, I think how he was making about $60K a year in today’s money at the current rough price of gold and silver.
But even when he was alive, Uncle Scam started debasing the currency with a new currency:
United States Notes, which were the first fiat currency issued during the Civil War. At least it had some gold and silver backing…
Invest in Jackson wheelbarrows:
https://mobileimages.lowes.com/productimages/bd87d69f-1342-4708-a116-d0d7404fb39a/64828482.jpg?size=xl
The personal Brink’s truck of the coming apocalypse.
And you wonder why the Germans voted for Adolf Hitler.
It looks like a darn fine purveyor of portable wealth Adi, but does it come with puncture resistant tires for SHTF shopping excursions?
Well, Hell, Landru,
No doubt the latest, “smart” version will have electronic TPMS, which will require an onboard battery, plus a “hardened” “control panel” (touch screen, no doubt).
But will it “call home” when you load up to hurriedly “buy” a loaf of bread before the price rises?